
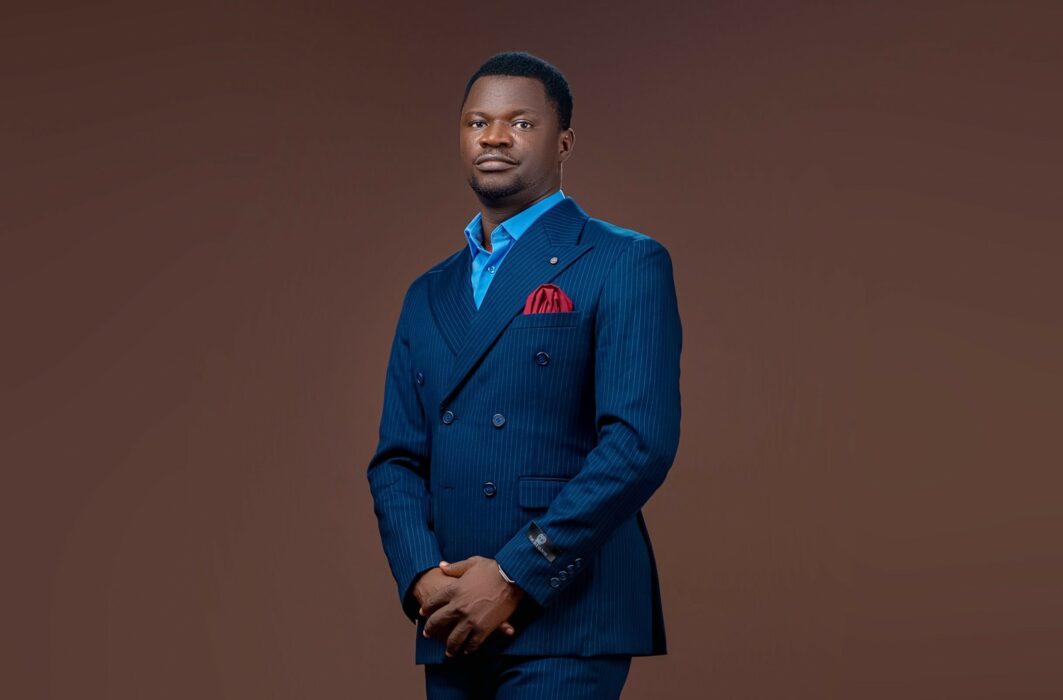
There was a business he reportedly wanted to establish for his wife. There was also a relative studying in the United Kingdom who needed money. Somewhere between those two responsibilities, the late Nigerian gospel singer Toluwanisings appeared to have faced a dilemma familiar to millions of Africans: how much of one’s earnings should go towards helping family, and how much should be reserved for building one’s own future?
In recordings that surfaced after his death, the singer, whose real name was Olayemi Bolaji, was allegedly heard expressing frustration over repeated financial demands from members of his maternal family.
One particular complaint has continued to attract public attention. The singer reportedly said he had postponed plans to start a business for his wife because of the cost of supporting a relative’s education abroad.
The recordings have not been independently authenticated, and members of his extended family have disputed aspects of the allegations. Nevertheless, the controversy has reopened an uncomfortable conversation about the financial responsibilities placed on successful family members.
It is a conversation that extends far beyond the gospel music industry.
In many Nigerian households, the first person to become financially stable automatically assumes responsibilities that extend beyond their immediate family. A younger sibling needs school fees. An uncle has a medical emergency. A cousin wants to travel abroad. A parent needs a new roof. Someone else needs capital to start a business.
Individually, the requests may appear reasonable. Collectively, they can consume years of earnings and leave the person providing the money struggling to achieve personal financial security.
The practice has a name: black tax.
And while helping relatives is hardly peculiar to Africa, the expectations surrounding it have become so deeply woven into family relationships that refusing a request can sometimes be interpreted as selfishness, arrogance or ingratitude.
The controversy surrounding Toluwanisings raises a difficult question: when does helping family become a burden that the giver can no longer afford?
The Man Everyone Appeared To Need
Toluwanisings died on October 14, 2026, leaving behind his wife, Elizabeth, and their children.
His death was followed by disputes and allegations involving members of his family. But it was the emergence of recordings allegedly documenting his financial frustrations that shifted public attention towards the responsibilities he reportedly carried while alive.
In one recording shared by social media personality Yinka TNT, the singer was purportedly heard complaining about requests involving millions of naira.
He reportedly said the demands had interfered with his plans to provide his wife with funds to start a business.
The relative at the centre of the dispute was identified as Shadrach Taiwo, also known as Taye, who was studying in the United Kingdom.
According to reports, Toluwanisings had been contributing towards his education. Yinka TNT subsequently alleged that the singer had paid £16,000 towards the relative’s studies. That figure has not been independently established through tuition records or bank statements.
The controversy intensified when fellow gospel singer Lanre Alewilese organised a ₦6 million fundraising effort towards Taye’s education after Toluwanisings’ death.
Alewilese later apologised to the widow, explaining that he had acted on information that the deceased had promised to pay the student’s outstanding tuition fees. He also said he had believed Taye was Toluwanisings’ biological brother.
The fundraiser became another source of public disagreement, particularly after reports emerged suggesting that the late singer had already expressed frustration over the financial commitment.
But the relatives have not remained silent.
In another recording circulated online, a woman identified as Taye’s mother reportedly questioned the singer’s complaints and referred to assistance her family had provided him in the past.
Another relative, Taiwo Olawoyin, denied allegations that he had exploited the singer financially or prevented him from establishing a business for his wife. He maintained that financial assistance he received was a loan rather than a gift.
These conflicting accounts leave important questions unresolved. How much money was actually paid? What agreements existed between the relatives? Were the payments freely offered, requested as assistance or regarded as obligations?
And did the singer’s earlier family circumstances influence his willingness to continue providing support?
There is no established evidence that these financial disagreements caused his death. That distinction matters. Financial pressure can be a serious source of distress, but attributing a person’s death to it requires evidence beyond recordings and social media allegations.
What the controversy does reveal is how complicated family financial relationships can become when generosity, gratitude and expectations overlap.
When Gratitude Becomes A Lifelong Debt
One of the most revealing aspects of the Toluwanisings controversy is the reported history of support he received from members of his maternal family.
Following his mother’s death, relatives reportedly played an important role in his upbringing.
In many Nigerian families, such assistance carries enormous moral significance.
A child raised by an aunt, uncle or older sibling may grow up believing that financial success comes with an obligation to repay the sacrifices made on their behalf.
There is nothing inherently wrong with that expectation. Supporting those who helped us through difficult circumstances is often an expression of gratitude and love.
The difficulty begins when repayment has no clearly understood limit.
How much does someone owe an aunt who raised them? Is paying a cousin’s school fees enough? Must the obligation continue until every member of the extended family becomes financially independent?
What happens when the person providing assistance gets married and begins raising children of their own?
These are questions families rarely discuss openly.
Instead, expectations are sometimes communicated through reminders of past sacrifices, comparisons with other successful relatives, or accusations that someone has forgotten where they came from.
The result can be a relationship in which money becomes a measure of gratitude.
Yet the situation is rarely straightforward. Relatives who sacrificed their own resources to raise a child may genuinely believe they deserve support in later life. The successful adult may also sincerely want to help.
The disagreement often begins not with the desire to assist, but with the amount being requested, the frequency of the demands and the giver’s ability to say no.
In Toluwanisings’ case, the alleged conflict between funding a relative’s overseas education and establishing a business for his wife makes the competing responsibilities particularly visible.
It raises another question: should the needs of an extended family member take precedence over the financial stability of a person’s spouse and children?
There may be no answer that satisfies everyone. But avoiding the conversation can create resentment that money alone cannot resolve.
Black Tax: An African Burden Or A Universal Responsibility?
The expression “black tax” is closely associated with South Africa, where it describes the financial responsibilities borne by many Black professionals who support parents, siblings and extended relatives.
The term gained prominence against the background of apartheid, which systematically restricted opportunities for Black South Africans to acquire wealth, property and quality education.
For many families, the first generation to obtain professional employment inherited responsibilities accumulated over decades of exclusion.
Their salaries were not simply personal income. They became resources for relatives who had never enjoyed the same opportunities.
Although the term emerged from a particular historical experience, the underlying practice is not exclusively African.
In India, the Philippines, the Caribbean and many immigrant communities, working adults routinely send money to parents and relatives. Family support can be regarded as an essential responsibility rather than an optional act of generosity.
In Nigeria, the practice predates the expression black tax.
Extended families have historically provided informal systems of welfare. Relatives contribute to education, weddings, funerals, healthcare and business ventures. Those who become financially comfortable are often expected to help others achieve similar stability.
In communities where government support is limited, these relationships can be the difference between a child remaining in school and dropping out, or between a sick relative receiving treatment and going without care.
Black tax, therefore, cannot be dismissed simply as exploitation.
It has helped produce doctors, lawyers, teachers, entrepreneurs and professionals whose education was funded by relatives.
It has also sustained families during unemployment, illness and economic crises.
But there is a difference between collective responsibility and unlimited financial dependence.
When one person’s salary becomes the permanent solution to everyone else’s problems, the arrangement can undermine the very financial security that makes the support possible.
The Billions Moving Between Families
The economic importance of family financial support is enormous, even if its exact value cannot be calculated.
According to World Bank data, Nigeria received approximately $22.8 billion in personal remittances in 2025, equivalent to about 7.8 per cent of its gross domestic product.
That is a substantial flow of money into an economy where many households depend on private support to meet everyday expenses.
However, remittances and black tax are not interchangeable.
Remittance statistics capture international transfers, which may include family support, savings, and other personal payments. Black tax also includes money transferred within Nigeria, often through informal arrangements that are not separately measured.
A civil servant in Abuja paying the rent of a sibling in Kaduna, a trader in Lagos covering hospital bills for parents in Osun, or an engineer in Port Harcourt supporting several younger relatives may all be carrying black tax.
Such payments rarely appear as a distinct category in national economic reports.
Yet they influence household consumption, education, healthcare, savings and investment.
Money sent to a parent may be spent immediately on food and medicine. School fees paid for a sibling support education and potentially improve that person’s future earning capacity. Capital provided to a relative may establish a business that eventually employs others.
These are genuine economic benefits.
But there is another side to the equation.
A person who spends a significant portion of monthly earnings supporting relatives may be unable to save for retirement, purchase a home, build an emergency fund or invest in a business.
READ ALSO:
- Netizens Berate Family As Revelations Surface On How Toluwanisings Was Pressured Financially To Death
- FG Considers Electric Buses To Ease Nigerians’ Transport Burden
- Oyo Police Arraign 2 Over False Publications, Defamation, Video Of Late Singer Toluwanisings
The immediate needs of one generation can consume the resources that might otherwise secure the next.
This is why black tax should be examined not only as a cultural practice but also as an economic question.
When relatives consistently pay for healthcare, education and basic welfare, they are helping to fill gaps left by inadequate public services and social protection.
The family becomes an informal welfare institution, funded largely by those fortunate enough to have a steady income.
But unlike formal welfare systems, these arrangements often have no budgets, eligibility rules or clear limits.
The person expected to provide assistance may have little control over how many people become dependent on their earnings.
And when that person experiences unemployment, illness or financial difficulty, the entire support structure may become vulnerable.
From Nigeria To The United Kingdom: A Different Kind Of Black Tax
What makes the Toluwanisings case unusual is the direction of the reported financial support.
In the popular Nigerian imagination, the relative living abroad is often regarded as the successful family member.
Migration is frequently associated with better employment opportunities, stronger currencies and the possibility of sending money home.
Families sometimes contribute heavily towards a relative’s relocation with the expectation that the investment will eventually benefit others.
But Toluwanisings’ reported experience presents the reverse arrangement: a Nigerian-based musician allegedly funding the education of a relative living in the United Kingdom.
This does not automatically mean the relative was financially comfortable.
International students in the UK can face substantial tuition fees, accommodation costs and restrictions on the number of hours they may work during term time. Some depend heavily on sponsors and relatives to complete their studies.
Nevertheless, the reported arrangement raises questions about the financial expectations attached to migration.
Who should bear the cost when a relative chooses to study abroad? Should a family member at home be expected to finance that decision indefinitely? And what happens when the sponsor’s own household has competing needs?
There is also the assumption that overseas education is an investment for the entire family.
A student who eventually secures employment abroad may later support parents and siblings, repay earlier assistance or create opportunities for others.
But such outcomes are not guaranteed.
Employment prospects, immigration rules, exchange rates and the cost of living can all affect whether the investment produces the anticipated returns.
For the person financing the education, the expenses are immediate. The potential benefits may be years away.
That imbalance becomes especially difficult when the financial commitment is open-ended.
In Toluwanisings’ case, the alleged decision to delay his wife’s business plans illustrates the possible opportunity cost.
Money directed towards one person’s education is money unavailable for another purpose.
The issue is not whether overseas education is worthwhile. It is whether a sponsor can afford the commitment without compromising the financial security of their own household.
The People Carrying Entire Families
Behind the public controversy are countless Nigerians navigating similar responsibilities without attracting attention.
Consider the financial choices facing a young professional who earns enough to maintain a modest household but also contributes to parents’ medication costs, younger siblings’ school fees, and relatives’ emergencies.
A salary increase may not translate into improved living conditions. Instead, it may attract additional requests from people who believe the worker can now afford to give more.
For some, this delays marriage, homeownership or business investment. Others take loans to meet family expectations or conceal their earnings to avoid being asked for money.
There are also those who willingly make these sacrifices because they remember what it meant to grow up without financial support.
For them, helping family is not a burden but an achievement.
A sibling’s graduation, a parent’s successful surgery or a relative’s thriving business can provide satisfaction that cannot be measured solely in money.
Both experiences deserve recognition.
The distinction lies in whether the assistance is sustainable and whether the giver retains the freedom to make financial decisions.
A family contribution made willingly, within an agreed budget, is different from a demand accompanied by threats, humiliation or accusations of ingratitude.
The pressure can also be emotional.
Someone who has supported relatives for years may feel unable to admit that their financial situation has changed. A struggling business owner may continue sending money to maintain an image of success. A salaried worker may fear that refusing one request will damage relationships built over a lifetime.
In some families, the person who gives the most is also the person expected to complain the least.
Their financial difficulties remain invisible because everyone assumes they are doing well.
This is one of the less discussed consequences of black tax: the expectation that the provider must always be capable of providing.
Who Protects The Provider?
The controversy surrounding Toluwanisings has generated anger, sympathy and conflicting accusations. But beyond the arguments about individual relatives lies a question that many families need to confront.
Who takes responsibility for the person everyone depends on?
Financial advisers often encourage people supporting extended families to establish clear budgets, separate emergency savings from discretionary assistance, and communicate what they can realistically afford.
Such boundaries may sound straightforward, but enforcing them can be difficult in families where money is closely tied to affection, respect and gratitude.
A refusal may be interpreted as rejection.
A decision to prioritise a spouse or child may be viewed as abandoning the extended family.
Yet sustainable support requires limits.
Parents need healthcare. Children need education. Relatives may require temporary assistance. But the person providing the money also needs savings, insurance, investment and the opportunity to plan for old age.
Without those protections, today’s provider may become tomorrow’s dependent.
Families can also distinguish between assistance that addresses an immediate emergency and support that creates long-term independence.
Paying school fees, providing vocational training or helping establish a viable business may reduce future dependence. Repeatedly financing expenses without a clear plan can produce the opposite result.
There is an equally important responsibility on those receiving support.
Gratitude should not be measured by how much more a relative is willing to sacrifice. Nor should past assistance automatically create an unlimited claim on someone’s future earnings.
Family relationships are strongest when support is accompanied by understanding of what the giver can afford.
Toluwanisings’ relatives have offered differing accounts of the financial arrangements at the centre of the controversy. Those accounts deserve careful examination, and no conclusion about responsibility for his death should be drawn from the allegations alone.
But the wider debate remains relevant regardless of how the family dispute is ultimately resolved.
In a country where many households depend on one another to survive, black tax will not disappear simply because younger people begin questioning it.
Nor should it necessarily disappear.
Family solidarity remains one of the most important resources available to people facing economic hardship.
The challenge is to preserve that solidarity without turning financial success into a lifelong obligation that leaves the giver with little security of their own.
For every public figure whose family responsibilities become the subject of national debate, there are many ordinary Nigerians quietly making similar decisions.
Some are postponing business plans to educate younger siblings. Others are sacrificing retirement savings to support ageing parents. Some are financing relatives abroad while struggling to meet expenses at home.
They may never describe what they do as black tax. To them, it is simply what family requires.
But perhaps the question should no longer be how much one person is willing to give.
It should also be how much that person can give without losing the opportunity to build a life of their own.
Because the true measure of family support should not be how much one person sacrifices, but whether everyone, including the person paying the bills, has a fair chance at a secure future.

